Kitsap Home Prices: What $500K, $800K and $1.5M Buy
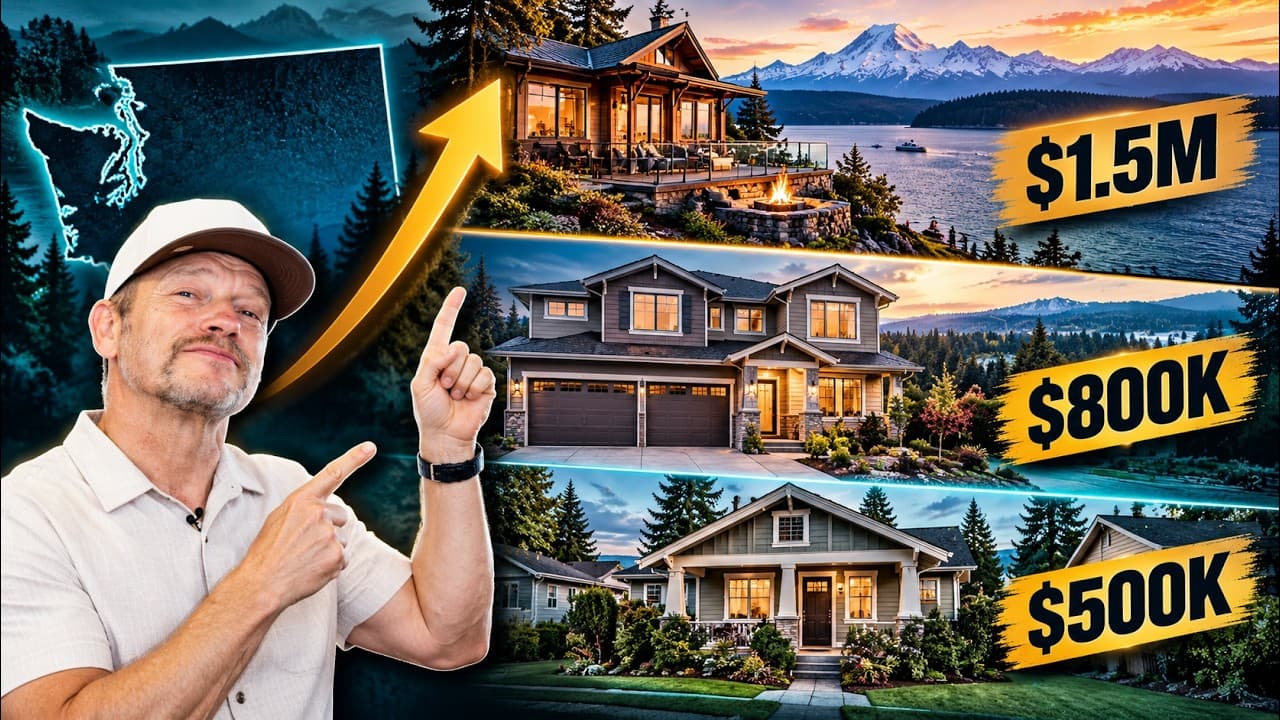
In Kitsap County in 2026, $500,000 buys a foothold, $800,000 buys the sweet spot, and $1.5 million buys the view tier. With the September 2026 county median at $595,000, $500K is the entry floor for a single-family home, $800K is the move-up tier where you stop compromising, and $1.5M gets you true waterfront or acreage. What actually decides whether a tier is comfortable is the monthly payment, and at 7.32% that number deserves more of your attention than the sticker price.
Almost every buyer I work with starts with a budget and a blank stare. They know what they can spend. They have no idea what it buys out here. That gap is where people overpay, or get priced out of the very thing they moved here for. I price this market every week and I write the offers, so here's the honest version of the Kitsap price ladder, rung by rung, with the money math attached.
Key Takeaways
- $500K is the floor now, not the middle. Kitsap's single-family median was $595,000 in September 2026, so the $500K buyer is shopping below the middle of the market.
- At $500K you pick two of three: location, condition or size. In-town Bremerton is usually the best value play at this rung.
- $800K is the sweet spot. It's comfortably above the median, it's the deepest part of the market, and it's where sellers are most willing to negotiate right now.
- $1.5M buys the view tier, true Hood Canal or Puget Sound waterfront, or 5 to 20 acres. On Bainbridge Island it buys a nice, ordinary house.
- Size yourself by the monthly payment, not the price. At the October 22 Freddie Mac average of 7.32%, principal and interest alone on an $800K home with 20% down is about $4,396 a month, before taxes and insurance.
- The carry is negotiable too. Seller-paid rate buydowns are back on the table at $800K and up, within limits your loan program sets.
Your Budget Buys a Tier, Not a House
Here's what most people do. They pick a number, open a search app, sort by price, and assume whatever pops up is what their money gets. Then they anchor on square footage like they're buying a spreadsheet.
In Kitsap County your budget doesn't buy a house. It buys a tier, and the tier is a package: location, land, condition, water access, commute and carrying cost, all bundled together.
The same $800,000 can be a brand-new four-bedroom in Silverdale, a fixer on the water you'll pour another $300,000 or more into, or a house and a shop on acreage in South Kitsap. Square footage is the least interesting thing your money decides.
Where the market sits right now
Before we climb the ladder, here's the floor it stands on. These are NWMLS single-family figures for September 2026.
| Measure | Kitsap County, September 2026 |
|---|---|
| Median sale price | $595,000 |
| Change from September 2025 | +1.8% |
| Closed sales | 313 |
| Active listings | 865 |
| Months of supply | 3.0 |
Three months of supply is still a seller's market by any normal measure. Balanced is usually described as four to six. Prices aren't running away, though. A 1.8% annual gain is a market that's tight, not overheated.
The $500K Foothold
With the median at $595,000, $500,000 is no longer a comfortable middle. It's the foothold. The good news is that the foothold is real. You can still buy a single-family home here at $500K. You just have to know the rule of this tier.
You buy location, condition, or size. Pick two. Rarely all three.
The best value play: in-town Bremerton
The best $500K value in the county right now is in-town Bremerton, including East Bremerton and Manette. You get an established craftsman or rambler, you're on city water and sewer instead of well and septic, and you're as close as you can get to the Seattle fast ferry.
The numbers back that up. Here's how the NWMLS area medians lined up in September 2026.
Source: NWMLS Breakouts, single-family, September 2026. Information and statistics compiled and reported by the Northwest Multiple Listing Service.
See the numbers
| Item | Value |
|---|---|
| West Bremerton | $450,000 |
| East Central Kitsap | $489,000 |
| Port Orchard | $519,999 |
| East Bremerton | $530,000 |
| Silverdale | $589,700 |
| Retsil / Manchester | $590,000 |
| Kitsap County | $595,000 |
| South Kitsap, west of Hwy 16 | $629,990 |
One caveat on the ferry. Kitsap Transit cut the Bremerton fast ferry schedule on September 1, so "close to the boat" means fewer boats than it did last summer. If the commute is part of why you're looking at Bremerton, read what the fast ferry cut costs your commute before you write an offer.
The other two swaps at $500K
| If you want | Where it points | What you trade |
|---|---|---|
| Location and condition | In-town Bremerton, East Bremerton, Manette | Size, and often an older home |
| Newer and low-maintenance | Silverdale townhome or condo | Square footage and a yard |
| Space and land | Further out in South Kitsap | Commute time, and you're on well and septic |
None of those are wrong. You just have to know which swap you're making before you fall for a listing photo.
What $500K demands from you
Be honest about two things at this rung.
First, you're often buying an older home, which means older systems. Inspect hard. Roof, sewer line, electrical panel, heating. Pull the public records too. I wrote up the six records I check before buying a Washington home, and every one of them matters more when the budget is tight.
Second, this is the most competitive, fastest-moving band in the county. The most buyers are fishing right here, so you have the least leverage. Be pre-approved, inspection-ready and decisive. The buyers who win at $500K did their homework before the right house showed up, not after.
The $800K Sweet Spot
This is where most of my move-up and relocation buyers land. At $800,000 you're comfortably above the county median, and you get to pick your adventure.
Three ways to spend $800K
| What you want | Where it points | What $800K typically buys |
|---|---|---|
| New and central | Silverdale | A modern four-bedroom with a real garage, minutes from the hospital and the retail core |
| Charm and ferry access | Poulsbo, Kingston | Newer construction or a character home near the boats |
| Land | South Kitsap, about 15 minutes out | A solid house on 2.5 to 5 acres, or 10 acres with a little less house, room for a shop, a garden and animals |
This is the tier where you stop trading condition for location, or space for newness. You usually get two of those three at once. That's what makes it the sweet spot.
Why $800K is where the leverage is
It's also the widest, deepest part of the market. The most move-in-ready homes live here, which means more choice. And in a 2026 market where a lot of owners are sitting on old low-rate mortgages, the sellers who do list at this level are often more willing to negotiate than the ones at the bottom of the market.
Negotiating room is real money. My buyers have averaged 95.48% of list price across every market cycle, roughly four and a half percent under asking. That doesn't happen by accident. It happens by knowing which tier has slack in it and which doesn't, and right now the slack is above the median, not below it.
For buyers coming from King County or California, $800,000 here feels like a different planet from what it buys over there. That gap is the whole reason a lot of you are reading this. I'll come back to it at the end.
The $1.5M View Tier
At $1.5 million the character of the market changes. You cross into the view tier: true waterfront, real acreage estates, the homes with the mountain and water sightlines that make people stop the car.
What $1.5M buys, by area
| Area | What $1.5M typically buys |
|---|---|
| Hood Canal | Genuine low-bank waterfront with the Olympics across the water |
| Puget Sound side (Manchester, Indianola) | Bluff and beach homes looking back at the shipping lanes, and the Seattle skyline on a clear day |
| Bainbridge Island | A nice non-waterfront home or a modest water view, not the trophy |
| Rural Kitsap | A real estate: 5 to 20 acres, a custom home, a shop or barn, gated and private |
Bainbridge deserves a straight answer. The island's median sale price has run well north of $1 million all year (it was $1,369,000 in the second quarter of 2026, per NWMLS-based quarterly figures). So $1.5M gets you onto the island, but it doesn't get you the waterfront house you pictured. That's the Bainbridge premium.
Waterfront is a different animal
Buying on the water isn't buying a house with a view. It's tidelands, bulkhead condition, erosion, drainage, and well and septic on many of these properties. That's real due diligence, not a formality. Before you tour anything on the water, read my guide to searching, inspecting and zoning Kitsap waterfront.
The buyer pool at this level is small, so these homes tend to sit longer. For a patient, prepared buyer, that's leverage. The negotiating room you don't have at $500K is sitting right here.
The Location Tax
Here's the part nobody puts in a cost-of-living article. The same dollar buys radically different homes depending on where in the county you point it. Your budget sets the tier. Your submarket sets how far that tier stretches. I call it the location tax.
The same $500K is a comfortable in-town home in Bremerton and close to land-only on Bainbridge. The same $1.5M is the very top of the Bremerton market, a true waterfront estate in Seabeck, and a nice, modest home on Bainbridge.
Neither is good or bad. It's leverage you get to aim.
Hold one thing still and let the rest move
Run the decision in the order that fits your life.
- If a specific town is non-negotiable (your job, your family, the ferry), hold the location and let it set your tier.
- If the lifestyle is non-negotiable (water, land, walkability), hold that and let geography pick the town that delivers it for the least money.
The mistake is holding the dollar amount rigid and letting it pick the town for you by accident. Your budget is one dial. The location tax is the second dial. Turn both on purpose and you can buy a noticeably better life for the same money. If you're not sure which towns fit, my Find Your Town tool asks four questions about your commute and priorities and gives you a shortlist, with the honest catch on each one.
The Monthly Carry Matters More Than the Price
The purchase price is the headline. The monthly carry is the story. In this rate environment your sticker price is really just the entry fee to a monthly commitment, and that monthly number is what decides whether a tier is comfortable or a cage.
What each rung costs per month
Freddie Mac's weekly survey had the 30-year fixed averaging 7.32% as of October 22, 2026, down from 7.40% the week before and up from 6.19% a year earlier. Here's what that means for principal and interest at each rung, with 20% down. This is my arithmetic on that published rate, not a lender quote.
| Price | Loan (20% down) | Monthly P&I at 7.32% | Monthly P&I at 6.19% | Difference |
|---|---|---|---|---|
| $500,000 | $400,000 | $2,748 | $2,447 | $301 |
| $595,000 (county median) | $476,000 | $3,270 | $2,912 | $358 |
| $800,000 | $640,000 | $4,396 | $3,916 | $480 |
| $1,500,000 | $1,200,000 | $8,243 | $7,342 | $901 |
Two notes on that table. A $1.2 million loan is a jumbo loan, and jumbo pricing doesn't always track the Freddie Mac average, so treat that row as a rough guide. And the survey is an average for borrowers with strong credit and 20% down. Your rate depends on your credit, your loan type and the day you lock. I covered how to shop it in comparing mortgage rates from local lenders.
What the table leaves out
Principal and interest is only part of the payment. Add these before you decide a tier is affordable:
- Property tax. It depends on the stack of taxing districts the parcel sits in (school, fire, city, library), so two homes at the same price can carry different bills. Look up the actual parcel on the Kitsap County Assessor's site before you offer, rather than trusting a search app's estimate.
- Homeowners insurance. Premiums have been climbing, and on the water they climb faster.
- Rural carry. Well maintenance, septic pumping and inspection, a generator for winter outages, longer service calls. A rural or waterfront home costs meaningfully more to run than its in-town twin at the same price.
Size yourself by the full monthly number, not the headline. The sticker gets you in the door. The carry is what you live with for the next decade.
The Carry Is Negotiable Too
Most buyers fight over one number, the price. In this market you can negotiate the carry as well.
How a seller-paid 2-1 buydown works
With a 2-1 buydown, the seller pays money up front so your rate is two points lower in year one and one point lower in year two, before it settles at the full note rate in year three. Here's my arithmetic on an $800,000 purchase with 20% down at 7.32%.
| Year | Rate | Monthly P&I |
|---|---|---|
| Year 1 | 5.32% | $3,562 |
| Year 2 | 6.32% | $3,970 |
| Year 3 onward | 7.32% | $4,396 |
The cost of that subsidy is the payment difference over the two years, about $15,100 on this example, or roughly 1.9% of the price. That's a real concession, but it's often an easier ask of a motivated seller than a $15,000 price cut, and it lands directly in your monthly budget.
The rules that limit it
Two rules matter here, and they come from the loan program, not from me.
- You still qualify at the full rate. On a conventional loan, Fannie Mae qualifies the borrower at the note rate, not the bought-down rate. A buydown eases your first two years. It doesn't stretch what you can borrow.
- Seller contributions are capped. A seller-funded buydown counts toward the interested party contribution limit. On a conventional loan for a primary residence, that limit is 3% of the price with less than 10% down, 6% with 10% to 25% down, and 9% with more than 25% down. FHA and VA have their own limits.
Those limits come from Fannie Mae's Selling Guide. Your lender confirms what applies to your specific loan before you write it into an offer.
The Kitsap Arbitrage
Here's the number I think matters more than $500K, $800K or $1.5M. It's the multiplier.
In my experience, the newer four-bedroom in Silverdale that sits in the $800K sweet spot here would be something like $1.4 to $1.8 million in much of King County. The $1.5M Kitsap waterfront estate with the Olympics across the water would run $3 to $4 million or more for comparable waterfront on the Eastside or in Seattle. Those are my comparisons from working both sides of the water, not a published statistic, but the direction isn't close.
The ferry everyone treats as a downside is the toll booth on that arbitrage. A short stretch of water stands between you and a price tag that roughly doubles.
Why the window matters
Right now a lot of move-up sellers are staying put, and patient buyers have leverage at the $800K and $1.5M tiers. That leverage tends to disappear when rates ease and the whole chain unfreezes at once. When that happens, the upper tiers heat up fast.
I'm not telling you rates are about to drop. Nobody knows that. I'm telling you that the negotiating room exists today, at the tiers where it exists, and it won't wait for you.
What Does $500,000 Buy in Kitsap County in 2026?
At $500,000 you can still buy a single-family home in Kitsap County, but it's below the September 2026 county median of $595,000. Expect to choose two of three: location, condition or size. The strongest value is usually in-town Bremerton, where West Bremerton's median was $450,000 and East Bremerton's was $530,000 in September. You'll often be buying an older home, so a thorough inspection matters more here than anywhere.
What Is the Median Home Price in Kitsap County Right Now?
The NWMLS single-family median sale price for Kitsap County was $595,000 in September 2026, up 1.8% from a year earlier. There were 313 closed sales, 865 active listings, and 3.0 months of supply, which still favors sellers. Area medians ranged from $450,000 in West Bremerton to $629,990 in South Kitsap west of Highway 16.
How Much Is the Monthly Payment on an $800,000 Home in Kitsap County?
With 20% down and a 30-year fixed rate of 7.32% (the Freddie Mac average as of October 22, 2026), principal and interest on an $800,000 home comes to about $4,396 a month. Property taxes, homeowners insurance and any HOA dues come on top of that. At the 6.19% average a year earlier, the same loan would have been about $480 a month less.
Can a Seller Pay for a Mortgage Rate Buydown in Washington?
Yes. A seller can fund a temporary buydown, like a 2-1, as a concession in the purchase contract. On a conventional loan it counts toward the seller contribution cap, which is 3%, 6% or 9% of the price depending on your down payment, and you still qualify at the full note rate. Your lender confirms the limits for your loan type.
Final Thoughts
$500K is the foothold: location, condition or size, pick two, with in-town Bremerton as the best value play. $800K is the sweet spot, where most move-up buyers land and where sellers have the most room to negotiate. $1.5M is the view tier, true waterfront and acreage, unless you're on Bainbridge.
The two levers nobody hands you are the location tax and the carry. Aim your budget at the right part of the county on purpose, and size yourself by the monthly payment, not the sticker. The price gets you in the door. The payment is what you live with.
Market figures are NWMLS single-family statistics for September 2026. Information and statistics compiled and reported by the Northwest Multiple Listing Service. Mortgage rates are the Freddie Mac Primary Mortgage Market Survey average as of October 22, 2026, and update weekly. Payment figures are my own arithmetic for illustration, not a loan quote. This isn't financial or tax advice. Confirm rates and loan rules with your lender and tax figures with the Kitsap County Assessor.
Want this ladder mapped to your budget?
Tell me your number and what you're moving here for, and I'll tell you which tier and which part of the county gets you the most for it, and what it really costs to carry. Book a no-pressure call or reach me at (360) 777-7212.
Ready to look? Search every home for sale in Kitsap County. Already own here and thinking about moving up? Start with what your home is worth.